Gentex Corporation (GNTX)
Gentex invited us to visit their headquarters in Zeeland, MI as part of their annual Investor Day conference to showcase their manufacturing plants and new products, and to help us understand the management’s future guidance for the company. We interacted one-on-one with the senior leadership including the CEO, COO, and the CFO as well as gauged in thoughtful discussions with many research analysts from major investment banks who were invited alongside us. Before diving deeper into our thoughts about the conference, let’s revisit what Gentex does.
The Business
Gentex was established in 1974 pioneering in manufacturing photoelectric smoke alarms and other fire protection technologies. Since then, they have expanded and diversified significantly, notably in the automotive industry. Today, Gentex engages in designing, developing, and manufacturing dimmable glass technology for vehicle side-view mirrors as well as Full Display Mirrors (FDMs) that attach a real-time rear-view camera feed to a display on the rear-view mirror. While their automotive products segment focuses on operating virtually all the foregoing facilities, they have significant investments made in dimmable glasses including dimmable aircraft windows, car sunroofs & sun visors, printed circuit board assembly (PCBA), audio products, and medical equipment. They continue to make legacy fire protection products.
Main Product Segments
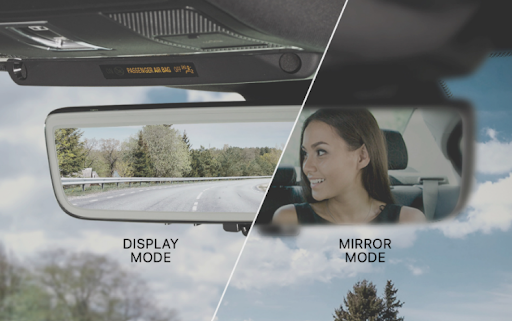
Mirrors: Gentex manufactures the side and rear-view mirrors that automatically dim (via chemical reactions) in bright lighting conditions (such as when someone behind you turns on their high beams at night). Chances are your car is equipped with a Gentex mirror as they have already had contractual partnerships with most major auto OEMs for decades.
Their newer product launch in the mirrors segment is the Full Display Mirror (FDM) that attaches an LCD screen to the rear-view mirror and provide a real-time camera feed behind the car. While it cannibalizes their own auto dimming mirrors segment (only for the rear-view, not the side-view mirrors), it upgrades the technology and 22 auto OEMs have already started equipping these in over 140 vehicle models (mostly higher-end car models and electric vehicles). As the technology becomes cheaper with scale expansion and less novelty, we expect huge sales growth in the FDM segment as the mirrors trickle down to mid and lower tier vehicles. We believe Gentex has a strong moat in the automotive mirrors business with a long-dated established network of customers, high switching costs, as well as a genuinely premium product that is hard to replicate by any competition anytime soon.
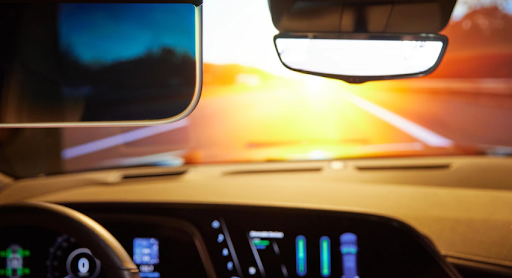
Dimmable Glass: This is an upcoming segment of products that Gentex showcased at the conference and includes two products: sunvisors and sunroofs.
Sunvisors: Gentex has pioneered a sunvisor design that is completely made of transparent glass. However, it can dim on demand with a single tap on a touch sensitive area of the glass as needed to block the sun. The glass has an ultrathin liquid filling inside that changes opacity as electricity is applied. The extent of the dimming can be positioned within a spectrum ranging from fully transparent to a translucent bluish tint to pitch black.
Sunroofs: The same technology would be used in the sunroof which will use a much larger piece of glass instead. Gentex called this segment Large-Area Dimmable or LAD. They has secured some OEM contracts to incorporate this technology with shipments starting in late 2027. We see this as a green space for growth as this new product category does not replace any existing Gentex product and will increase their average revenue per unit (ARPU) or vehicle. At the conference, we were shown live demos of the two products and a tour of the manufacturing stages. The production quality and capacity is robust. Gentex also already supplies this glass technology to Boeing 787 for passenger window dimming and has received new contracts for the 777 as well as Airbus A350, which is a good sign as it signifies that the tech is ready and not in a ‘development’ stage.
While the total addressable market is essentially all production cars, the uncertainty in adoption rates is an overhang. Firstly, the components are expensive and thus will probably only start to roll out in luxury cars first. Secondly, there are some businesses (such as AGC Glass Europe) that currently supply electrochromic sunroofs using PDLC technology that already have been equipped in a few cars models today. Gentex differentiates its dimmable glass by providing a multi-level light control including full pitch-black end while the competitors have just a clear and a translucent mode that still lets some sunlight in. They are also working on “memory” for the sunroof so that it stays dark for many days without drawing charge so that a vehicle can stay cool in a sunny parking lot. Gentex will need to leverage their OEM network to win more contracts to expand and gain from economies of scale, but we do see this segment as another opportunity for building a moat. As adoption increases over time, they see a transition into supplying just a lamination of the ultrathin liquid layer instead of manufacturing the whole glass panel. This will allow the OEMs to customize their sunroof or sunvisor glass design while also yielding Gentex attractive margins as they would just need to produce a homologous sheet of laminated liquid.
PCBA: This is another business segment that the Gentex leadership is very enthusiastic about. Gentex manufacturers all the electric components and circuits needed for all its products in-house. They plan to utilize its spare machinery into manufacturing and assembling printed circuit boards for automotive, aerospace, and non-automotive customers on a contract basis. These printed circuit boards can be used for making various electric components that caters to many businesses. The PCBA business segment would require little new capital investment as the physical machinery already exists as well as no R&D costs as it leverages a skill set that they already have in-house. Thus, the management believes PCBA will provide an extra layer of ‘free’ revenue to Gentex.
Gentex’s CEO sees a “giant void being created in the industry right now with electronics manufacturing fully dedicating their capacity to data centers.” They secured their first contract of about $180M with planned production starting in 2029. While the management sees the PCBA contributing $1B - $2B annually, we would like to remain very modest with our forecast estimates as we cannot be fully certain about how many contracts they will get in this new space, despite their network reach, and how profitable they will be.
Premium Audio Company (PAC): Gentex acquired Voxx International (PAC’s parent company) in April 2025 to enter the electronics audio devices industry. The core brands are Onkyo, Integra, and Klipsch making speakers and home sound systems.
Gentex was able to acquire PAC at a reasonable discount which has resulted in good value addition to the company. The segment is growing at a high rate and provides good profit margins which we see as a positive.
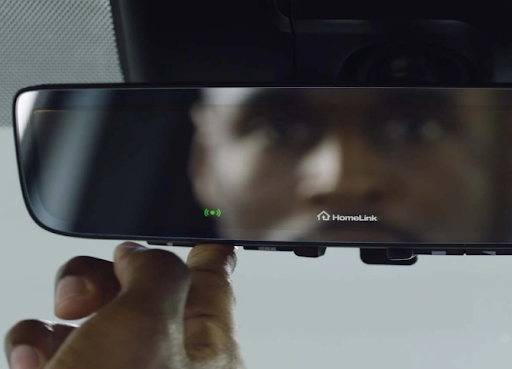
Others: Gentex’s HomeLink provides in‑vehicle control of garage doors, gates, and smart home devices, expanding into cloud‑connected home automation ecosystems. It generated approximately $330M in 2025 (or about 14% of total revenue). While the management is excited about expanding HomeLink with new features and capabilities, we don’t share the same excitement as them as we find little reason to why customers would want to access house controls from their car when smartphone apps for all such home devices already exist from competition. We have accounted for no (and even negative) growth in our model for this segment.
The Fire Protection segment manufactures photoelectric smoke alarms, CO detectors, and signaling devices, continuing Gentex’s original product heritage.
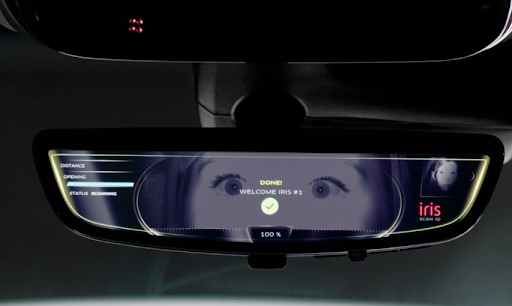
Finally, its biometrics and sensing work focuses on driver monitoring leveraging Gentex’s mirror‑integrated cameras and electronics capabilities.
Risks and Headwinds
Distraction: While the diversification efforts (in the form of PCBA and PAC) potentially provide high revenue opportunities with good growth rates, we also see this as a distraction to their main business automotive business, which is mirrors and dimmable glass. We would like them to ensure their focus remains on becoming a key part of the automotive supply chain. We feel that the management shares our view as, during the conference, they emphasized how little oversight the management would need to give to the PAC and PCBA business. They also briefly touched upon potentially selling the PAC business once it’s growth potential is captured.
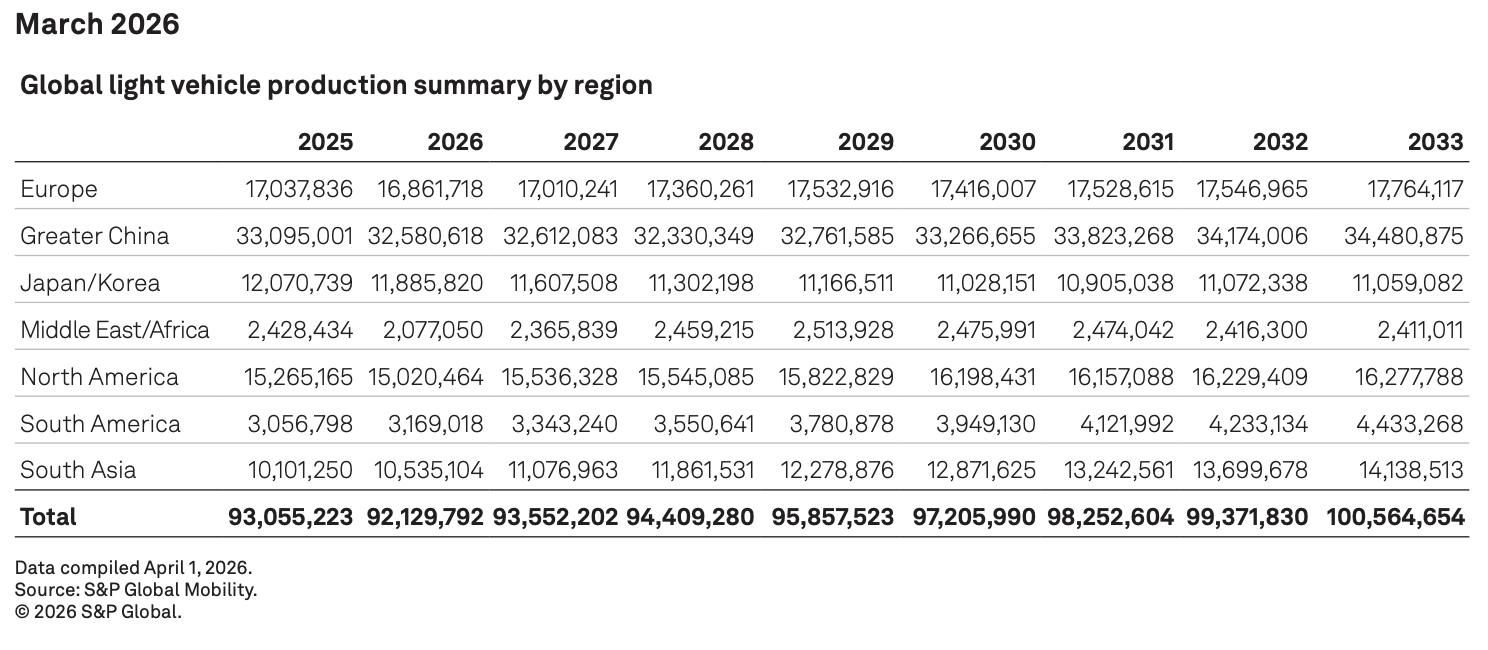
Macro: Light Vehicle production is estimated to decline about 1% in 2026 compared to last year. Despite lesser number of cars produced, Gentex has grown their revenue this year through winning more auto contracts for their FDMs. However, the question remains about the growth of the auto industry in the long term as it directly correlates to Gentex’s revenue and profits. The table below provides a forecast of global light vehicle production from S&P Global.
Input Costs: Prices for raw materials such as silver, gold, and ruthenium have recently been volatile, owing to conflicts and wars at the geopolitical stage, and adds a layer of uncertainty to the input costs in the production of the mirrors. Furthermore, semiconductors and memory chip prices have shot up rapidly due to global supply shortages caused by the massive AI data center buildout that consume many of these chips. This has directly impacted input costs on their digital products like FDM. The management has emphasized that they are re-developing manufacturing processes and product designs that uses fewer precious metals and completely removes the need for memory chips. Should this development materialize, the input costs can be well controlled in the long-term future.
Geographic Fracturing: The United States’ tariff policies with other nations globally has impacted Gentex’s business internationally. Their business in China shrunk by over 25% due to high tariffs. Their business also slowed down in the European market owing to higher tariffs and especially after losing a contract with Volkswagen on purchase of their mirrors. To counter the offset, the management disclosed that Gentex has invested in a manufacturing facility in Morocco that will assemble the final mirrors for the European market. Morocco has a favorable tariff policy with the European Union which should bring growth in sales and revenue.
Our Valuation
We obtain a Fair Value Estimate (FVE) of $34.61 per share price for GNTX. At its current trading price, we believe it to be at a significant discount. In our bear-case estimates, we account for a stagnant to slightly negative mirrors segment growth over the next decade given automotive production decline as well as assume that PCBA generates zero revenue. We also assume negative growth in PAC after 2028 and modest growth in dimmable glass segment. The bear-case estimate fetches a $24.28 per share price which is still at a 20% upside to current trading price of about $20 per share. In our bull-case estimate, as the automotive industry bounces back from its cyclical trough and with successful execution of the dimmable glass products and PCBA business, we see the share reaching a $40.27 per share price.
Summary
We believe Gentex represents an attractive investment opportunity at this stage. Gentex continues to maintain a fortress balance sheet with zero net debt that allows them freedom of capital allocation and high financial stability. The market has consistently lowered their sentiment in their success as represented by the steady decline in the stock price for the last few years. The management, on the other hand, has accelerated their share repurchase commitments to approximately 30M more shares over the next 2.5 years as they see the stock price at steep discount. That will erase approximately 15% of outstanding shares. We see that as a testimony of a company that truly believes in its business and will prove very profitable for the shareholders as the market realizes Gentex’s enterprise value over time.